Tuesday, 9 November 2010

External Board Performance Review - What does it look like?

External Board Performance Review Research

The Corporate Development Directorate of De Montfort University (DMU) wishes to develop an External Board Review methodology that adds real value to the Board whilst also satisfying the requirement of the Corporate Governance Code June 2010.

Approaching this research from first principles and then by comparison with existing methodologies, DMU has developed the following outline:

1. Introduction and presentation of process to Board

· Arrange Non-disclosure agreement

2. Analyse a selection of agendas, papers, and minutes from Board and Board Committee meetings

· Feed back findings/comments to Chairman (/Senior INED)

· Gain approval for next phase

3. Observe Board and Committee meetings

· Feed back findings/comments to Chairman (/Senior INED)

· Gain approval for next phase

4. Interview all Board members

· Feed back findings/comments to Chairman (/Senior INED)

· Gain approval for next phase

5. Write and present 1st draft of report to Chairman and agree (iterative process)

6. Finalise report and present to Board

(Questionnaires may also be used at various stages where appropriate)

To allow completion of the process within a three-month time frame it should, if possible, be planned to take place at a phase in the cycle where the Board and all its Committees are scheduled to meet within such a period.

By engaging in this research the Board of the host organisation will have gained much beneficial insight into its operation and should have a report that it could use as an External Board Assessment Report should it wish to do so.

Sir David Walker - Annual External Board Performance Reviews?

The Chairman of a City firm I met last week referred to comments made by Sir David in a dinner speech earlier this year. It was reported to me that Sir David would have liked to have recommend that external board performance reviews were undertaken annually but that there were not sufficient (in number and or quality?) suppliers in the market to undertake this work.

In some senses this was music to my ears as we undertake the research and development to allow us to offer this service!

We are currently offering a no-fee external board review as part of the research. One organisation has already taken us up on this offer and we are looking for two more. If your organisation would be interested, or if you know of an organisation that might be interested, please get in touch.

Monday, 25 October 2010

Vince Cable wants your opinion


Vince Cable, Secretary of State for Business today launched a review to consider whether there are failures in corporate governance and the markets. He is calling on company directors, shareholders and other investors to contribute their views.

The call for evidence launched today, ‘A Long Term Focus for Corporate Britain’, aims to investigate issues including; the problems of short-termism, investor engagement, directors’ remuneration and – following on from last week’s announcement by the Takeover Panel – the economic case for takeovers. It also asks:

  • Do boards understand the long-term implications of takeovers, and communicate the long-term implications of bids effectively?
  • What are the implications of the changing nature of UK share ownership for corporate governance and capital markets? Whether disclosure of directors’ pay should be more transparent?
  • Do shareholders and investors focus too much on the short-term?

Vince Cable, Business Secretary said:

“The UK has led the world in developing high standards of corporate governance. The first stewardship rules for investors, the first corporate governance framework for companies and the most comprehensive takeover code.

"Now is the time to look to the future and take a wider view on how these can work together. Well functioning capital markets are vital to productivity, growth and the future prosperity of the UK.

"We need to ask ourselves what are the factors influencing short-term decisions, the reasons for the growth of directors’ pay and why economically damaging takeovers still take place? I recognise that the best solutions will come from businesses and that regulation is not the only option. That is why today I am calling on all companies and individuals to put forward their ideas.”

The consultation will run for 12 weeks, from today until Friday 14th January 2011.

Notes to editors:

1.
Today BIS launched a consultation, ‘A Long Term Focus for Corporate Britain’. This will run for 12 weeks and closes on Friday 14th January 2011.
2. Company directors, shareholders and other investors are invited to contribute. The consultation document can be found on the BIS website here: http://www.bis.gov.uk/Consultations
3. BIS' online newsroom contains the latest press notices, speeches, as well as video and images for download. It also features an up to date list of BIS press office contacts. See http://www.bis.gov.uk/newsroom for more information.

Risk Appetite - Hungry or Averse?!?

The whole area of risk assessment and risk management is increasingly important and under ever increasing scrutiny from regulators and investors alike. The Corporate Governance Code 201o re-inforces this emphasis, with requirements of the FSA for financial institutions taking it even further. Clarity about what is specifically required by regulators is however in short supply.

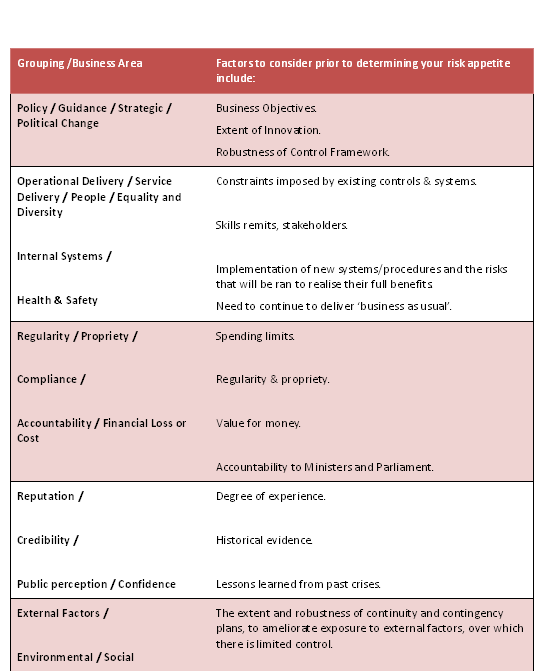
Looking at the response required by the FSA from his organisation, a CEO recently asked me about risk appetite represented numerically. In searching out an answer to this questions one of my researchers uncovered some interesting papers that may be of help to anyone looking at risk. I have inserted some graphical extracts below with the links to these papers should you want to read them in detail.

The KPMG paper gives a good oversight and the HM Treasury papers is excellent for detail.

"Understanding and articulating risk appetite" KPMG

Adapted from above


"Risk appetite - How hungry are you?" PWC
www.pwc.com/en_GX/gx/banking-capital-markets/pdf/risk_appetite.pdf


"Thinking about risk. Managing your risk appetite: A practitioners guide" HM Treasury


Wednesday, 13 October 2010

The FRC on Auditor Independence: It takes... four?

The use of auditors to carry out non-audit work for clients has long been contentious because the independence of the audit could be compromised by these additional ties. But exactly who is in charge of safeguarding auditor independence?

The Financial Reporting Council (FRC) has recently criticised the four biggest auditors, Deloitte, Ernst & Young, KPMG and PwC for doing too little to avoid conflicts of interest in providing clients with auditing services. The annual evaluations of the Big Four auditors, conducted by the FRC’s Audit Inspection Unit (AIU), have come amid increased regulatory scrutiny of the profession and its role in the financial crisis.

The AIU said Deloitte had committed an ethical breach in this area when it assigned two staff to an audit client to advise management for six months. PwC was also deemed to be guilty of an ethical slip when it acted as an actuary to an audit client’s pension scheme.

Paul George, director of the Professional Oversight Board which carried out the inspections, said the auditors “need to think more carefully about whether they can accept [certain types] of non-audit services.” (http://www.ft.com/cms/s/0/c09a15ea-bf6d-11df-965a-00144feab49a.html)

However, the auditors are not the only party responsible for avoiding conflict of interests in this area. Provision C.3.2 of the 2010 UK Corporate Governance Code states that a Board’s audit committee should

develop and implement policy on the engagement of the external auditor to supply non-audit services, taking into account relevant ethical guidance regarding the provision of non audit services by the external audit firm.

In the same provision, the role is further extended to the Board as a whole to whom the audit committee should report, “identifying any matters in respect of which it considers that action or improvement is needed and making recommendations as to the steps to be taken.”

And if the auditing companies, their clients, and the Boards of audited companies all flout their duties, there is provision for shareholders to step in. According to Code section C.3.7,

the annual report should explain to shareholders how, if the auditor provides non-audit services, auditor objectivity and independence is safeguarded

If shareholders are on the ball, they should challenge the Boards of investee companies over questionable external auditor engagement, especially given Principle 3 of the Stewardship Code detailing the ways in which “institutional investors should monitor their investee companies”.

The question arises whether the proportion of blame placed on auditing companies since the global financial downturn should be spread more widely. More importantly, is the FRC’s plethora of guidelines, published by multiple departments and aimed at numerous parties, blurring the lines of responsibility for some of the most crucial corporate governance issues?

Wednesday, 6 October 2010

Unlocking the Code: What do the changes mean for you? Continued...

The final major change to consider is the new Code’s guidelines on directors’ performance-related remuneration. Revisions around this issue appear in three places.

Remuneration

Firstly, new supporting principle D.1 instructs that the performance-related elements of executive directors’ remuneration should be designed to promote the long-term success of the company, as well as being stretching.

There is also an expanded provision, the new D.1.3, that discourages all forms of performance-related remuneration for NEDs, not only share options.

Finally, Schedule A includes amended performance-related remuneration provisions. The main changes are that:

· Performance conditions should be designed to promote the long-terms success of the company

· Non-financial performance metrics should be reflected in performance criteria where appropriate

· The company should consider using provisions that permit the company to reclaim variable components in exceptional circumstances of misstatement or misconduct

· Remuneration incentives should be compatible with risk policies and systems. The previous suggestion that incentives should be specifically risk-adjusted has been removed

Although, in most instances, performance-related elements of executive directors’ remuneration will already be aligned to the company’s long-term interests, remuneration packages should be revisited in light of the Code’s changed tone and focus in this area. In particular, the changes to Schedule A could require alterations to the terms of incentive schemes.

Tuesday, 28 September 2010


BP’s less than Best Practice

BP recently published the results of its internal inquiry into the causes of the Gulf of Mexico oil spill. Other oil majors have said they are examining their safety procedures in light of the report, and its release has sparked a wider debate about how the industry as a whole operates.

Among the accident report’s recommendations were strengthening procedures for conducting and interpreting well tests, bolstering the insurance on blow-out preventers, well control, cement testing and rig audit and verification.

But such practical safety recommendations are only effective if there are good communication lines between the Board, management and rig workers so that instructions and concerns are passed back and forth promptly.

In the dialogue between BP and Congress occurring soon after the spill, it emerged that, while BP engineers were exchanging emails long before the accident stating serious concerns over the safety of the Gulf’s Macondo well, the company’s House Energy Committee found no trace of those concerns reaching senior management.

The case points to a dangerously stubborn corporate culture that, according to a Financial Times article on the case, prevails in many well-established companies like BP that carry decades of distinguished history (http://www.ft.com/cms/s/0/5b89e194-820a-11df-938f-00144feabdc0.html). This culture can corrupt despite external signs of good practice. BP’s Board committee on Safety, Ethics and Assurance comprises four non-executive directors and met seven times last year with the then serving CEO, Tony Hayward, presenting to each meeting in person. Furthermore, the BP safety and operations audit team was in the midst of a three year task to audit all major operating sites worldwide and, according to a so-called independent expert appointed to report on safety at the US refineries, the tone of senior management and the Board was supportive in delivering optimum safety standards.

In response to this apparent discrepancy between the measures taken and the disastrous outcome, several investment professionals have insisted that the BP affair underlines the duty of owners to examine companies on safety. The argument runs that they should challenge companies based on such guidelines as the UK Corporate Governance Code, which states the responsibility of the Board for “determining the nature and extent of the significant risks it is willing to take in achieving its strategic objectives” and maintaining “sound risk management and internal control systems” (Main Principle C.2).

But even if an institutional shareholder had questioned the Board on its adherence to these guidelines prior to the spill, the Board would have responded with a rehearsed reassurance about the activities of the safety committee and audit team and the shareholder, obliged not to meddle with operating specifics, would have had little option for further action.

This state of affairs points to a lack of provision in global corporate governance for dealing with companies that display good Board level intentions that suffer weak execution down the management line. Unless shareholders, or another suitable party, are given the right and responsibility to dig deeper than policy statements and tick-box compliance messages, companies have the scope to quietly go on grossly mishandling safety – as well as economic and CSR – issues, with little disruption from onlookers.